
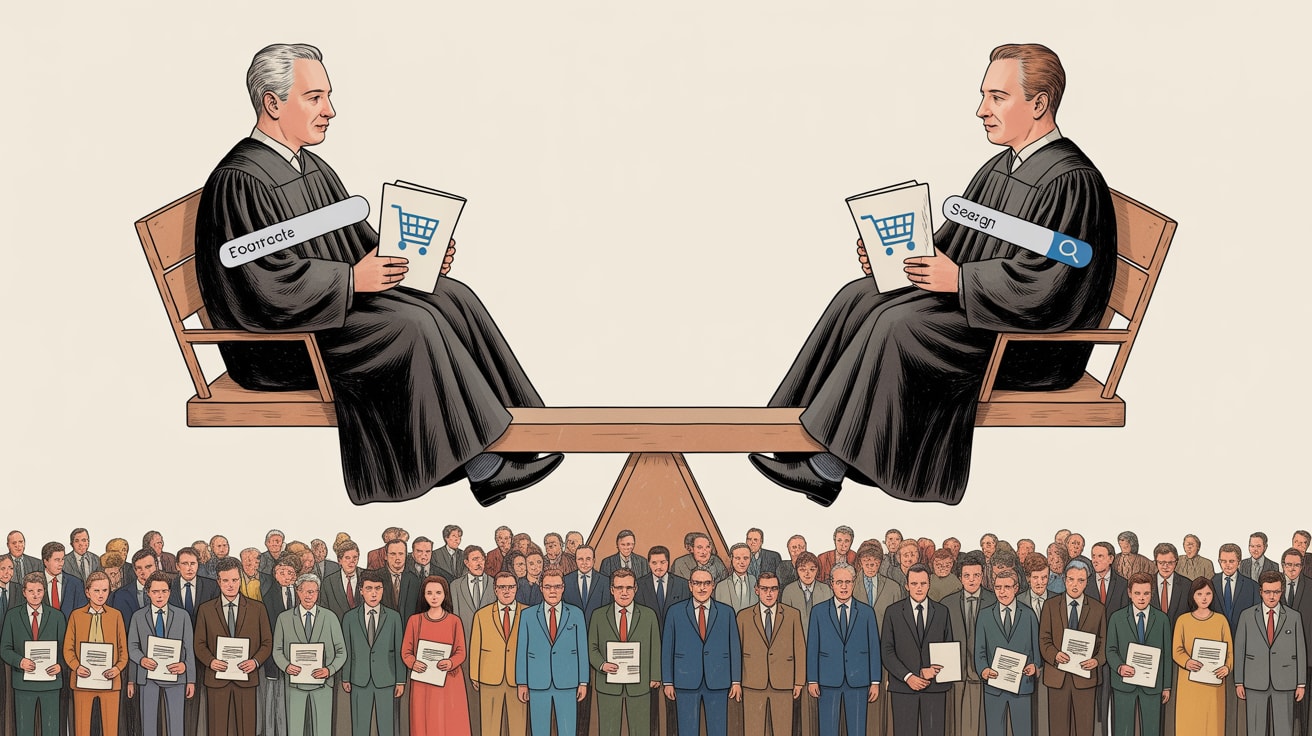
Amazon faces FTC charges over inflated ad pricing as Google escapes a breakup. Here's what the legal pressure on ad giants means for marketers in Southeast Asia.
The ad industry’s two most powerful platforms are having very different weeks in court — and neither outcome is actually good news for marketers who’ve been quietly assuming the system is working in their favour.
Google walks away from its antitrust case without a forced breakup of its ads business. Amazon walks in, facing FTC allegations that it systematically overcharged advertisers on ecommerce placements. Meanwhile, creator deal costs are quietly ballooning — not because creators got more expensive, but because the contract terms around usage rights have become a negotiation minefield. These aren’t isolated stories. They’re three data points pointing at the same structural problem: marketers are operating inside pricing architectures they don’t fully control or understand.
Google’s Escape Hatch Changes Nothing About Market Concentration
AdExchanger reports that despite being declared an online monopolist, Google will not be required to divest its ads business. For anyone hoping that regulatory action would structurally redistribute power in the open web ecosystem, this is a cold shower. The ruling affirms the finding of monopoly without imposing the remedy that would have mattered.
The practical implication for Southeast Asian brands is that the Google stack — Search, DV360, Campaign Manager, YouTube — remains vertically integrated and dominant. Teams running programmatic campaigns across markets like Vietnam, Thailand, or the Philippines will continue operating in an environment where the auctioneer, the exchange, and the DSP share a corporate parent. That’s not inherently sinister, but it does mean your CPM benchmarks and quality scores are shaped by an entity with structural incentives that don’t always align with yours. The strategic response isn’t to abandon Google — it’s to stop treating it as a neutral utility and start auditing it like a vendor with pricing power.
Amazon’s Ad Pricing Problem Is Everyone’s Problem
The FTC’s case against Amazon cuts closer to the bone for performance marketers. The allegation, as AdExchanger covers it, is that Amazon charged advertisers more than necessary for ecommerce placements — effectively inflating costs to protect its own retail margins. If substantiated, this would mean that brands running sponsored product campaigns on Lazada’s Amazon-influenced architecture, or directly on Amazon.sg, may have been paying a hidden premium baked into the auction mechanism itself.
Retail media is the fastest-growing ad category in Southeast Asia right now, with Shopee, Lazada, and Grab all expanding their first-party ad inventory. The Amazon case is a forcing function for a question brands should already be asking: how do you independently verify that auction-based pricing on a closed platform reflects genuine market demand? The answer today is: you largely can’t. Which is exactly why the FTC case matters beyond US borders — it establishes the legal and conceptual framework that regional regulators will eventually borrow.
Practical step: request impression-level cost reporting from every retail media partner and cross-reference against category benchmarks from independent measurement vendors. If a platform can’t provide it, that’s diagnostic information.
Creator Usage Rights Are Now a Hidden Media Cost
Digiday’s reporting on creator pricing surfaces something that media planners are increasingly factoring into influencer budgets across Southeast Asia: usage rights fees are materially inflating the cost of creator partnerships, and neither side of the negotiation table fully understands how to price them.
The structure is straightforward but routinely mishandled. A creator quotes a fee for producing content and posting it to their channel. The brand then wants to run that content as paid social, whitelist it through the creator’s handle, or repurpose it in OOH or retail contexts. Each of those use cases triggers a separate licensing fee — and there’s no standardised rate card. In markets like Indonesia or Thailand, where influencer marketing is a primary acquisition channel for FMCG and fashion brands, this ambiguity is quietly compounding campaign costs by 20–40% post-signature.
The fix is contractual, not creative. Build a usage rights matrix into every creator brief before pricing conversations begin — define platform scope, duration (90 days vs. 12 months is a significant cost delta), geographic rights, and paid amplification permissions. Treat it the same way you’d treat licensing a music track. Leaving it to post-production negotiation is how you end up with a great piece of content you legally can’t run.
CTV’s Governance Gap Is Coming for Southeast Asia Next
Slightly east of the Amazon headlines, India’s CTV and FAST ecosystem is taking a structurally important step: senior industry leaders convened a roundtable under Runn Media Labs to explore forming the India Connected TV & FAST Council (ICFC), according to AdTech Today. The goal is collective action on shared industry priorities — measurement standards, ad format consistency, inventory transparency.
This matters for Southeast Asia because the region is roughly 18 months behind India on CTV penetration curves, and the governance infrastructure gap is already visible. Samsung TV Plus, LG Channels, and local FAST platforms like PPTV (Thailand) and Vidio (Indonesia) are scaling without common measurement frameworks or identity standards. Advertisers are buying CTV inventory across the region without reliable reach deduplication or cross-platform frequency capping. India formalising a council now is a signal that the same conversation needs to start happening in Bangkok, Jakarta, and Manila before the inventory scales further without the rails.
Key Takeaways
- Audit your retail media spend on closed platforms — independent impression-level reporting is the minimum bar for cost accountability, and if a platform won’t provide it, price that risk into your planning.
- Build usage rights terms into creator briefs before pricing discussions, specifying platform, duration, geography, and paid amplification rights to eliminate the most common source of post-campaign cost inflation.
- Southeast Asian brands should be watching India’s CTV council formation closely — the measurement and identity standards being drafted there will likely become the regional template within two years.
The common thread across all three stories is the same one I keep coming back to in cookieless and clean room conversations: the infrastructure that determines what you pay and what you get is increasingly opaque, and the brands winning in this environment are the ones who’ve invested in the capability to interrogate it. The question isn’t whether you trust these platforms. It’s whether you’ve built the systems to verify.
At grzzly, we work with marketing and growth teams across Southeast Asia who are navigating exactly this — building the measurement architecture, vendor frameworks, and identity strategies that let you operate with clarity inside systems designed for opacity. If your ad stack has grown faster than your ability to audit it, that’s a conversation worth having. Let’s talk
Sources
- https://www.adexchanger.com/the-big-story/google-had-its-day-in-court-now-its-amazons-turn/
- https://digiday.com/media/marketers-say-usage-rights-are-driving-up-the-price-to-work-with-creators/
- https://adtechtoday.com/indias-ctv-fast-industry-comes-together-to-explore-formation-of-india-connected-tv-fast-council-icfc/
Written by
Rogue GrizzlyOperating at the contested frontier of cookieless targeting, clean rooms, and identity resolution. Comfortable where the infrastructure is shifting and the playbooks have not yet been written.