
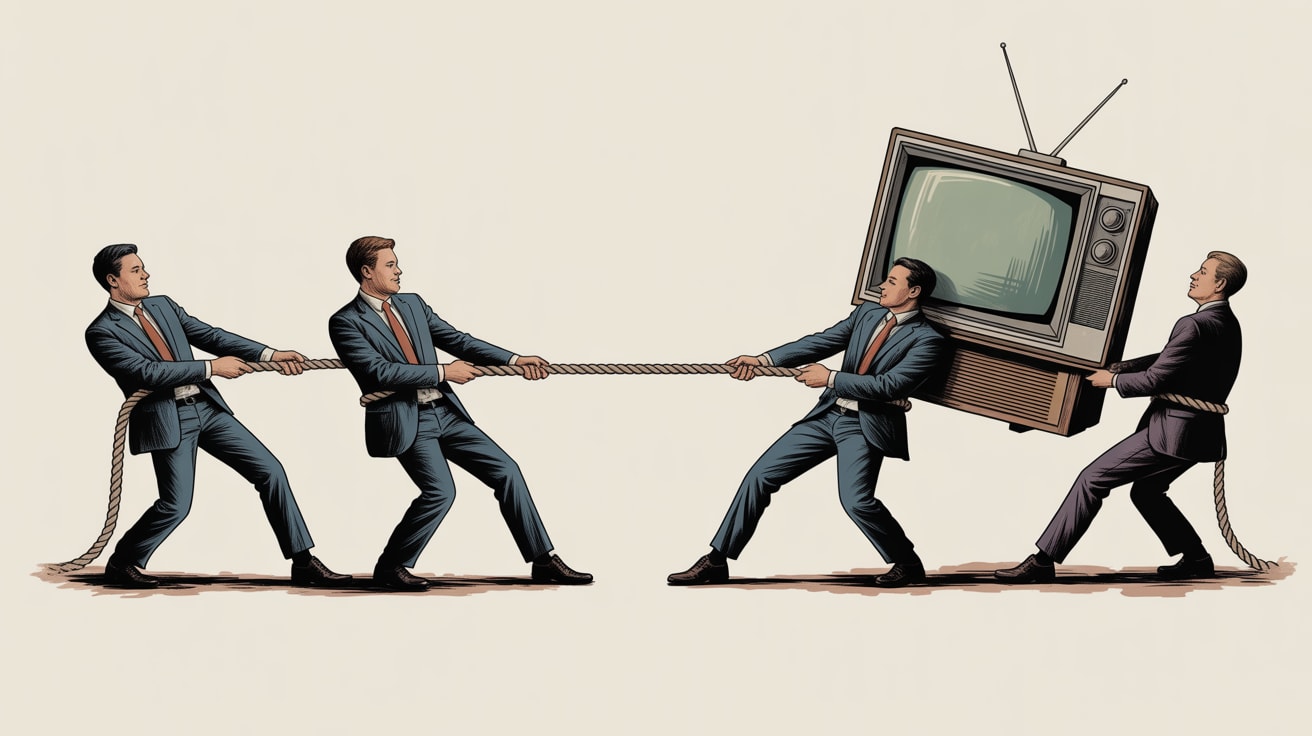
Alphonso's three-way exit options reveal how CTV ad tech is consolidating fast — and what that means for media buyers in Southeast Asia.
When a company has been locked in three years of legal combat with its own parent and is simultaneously fielding interest from a cable giant and a Koch Brothers-linked private equity vehicle, that’s not a distraction — it’s a signal. Alphonso’s exit saga, reported by AdExchanger, is one of the cleaner windows we’ve had into how CTV ad tech is actually valued when things get real.
Why Alphonso’s Exit Options Tell You More Than Its Revenue
Alphonso — LG Electronics’ ad tech division, best known for ACR (Automatic Content Recognition) data from LG smart TVs — filed a confidential S-1 in September 2025. Now it’s weighing three paths: a traditional IPO, a joint venture with Comcast, or a private equity deal reportedly valued around a billion dollars. The fact that all three are still live simultaneously isn’t indecision. It’s leverage.
What’s actually being valued here isn’t a demand-side platform or a campaign management UI. It’s first-party viewership signal at scale — the ability to tell advertisers what a household actually watched, not what they claimed to watch in a survey. That’s a structurally scarce asset as third-party data continues to erode. The IPO path tests public market appetite for that thesis. The Comcast JV path bundles it into linear-plus-streaming infrastructure. The PE path monetises it for patient capital. Three different buyers, same underlying bet.
WPP’s Legal Exposure and the Client Loyalty Question
Meanwhile, Digiday’s Michael Bürgi raises a question that sounds obvious but isn’t: do holding company legal problems actually move clients? WPP is currently navigating multiple court cases, and the conventional wisdom is that clients don’t switch agencies over litigation unless it directly affects deliverables or brand safety exposure.
Bürgi’s reporting suggests that’s largely correct — inertia is a powerful force in agency relationships, and the switching costs are real. But there’s a subtler risk that doesn’t show up in pitch losses: the talent drain that legal distraction triggers internally, and the procurement leverage it hands to clients during contract renewals. A holdco under legal pressure doesn’t necessarily lose accounts. It often just loses margin.
For independent agencies and boutique specialists, this is worth watching. Not because WPP clients are about to flood the market — they’re probably not — but because periods of holdco turbulence historically create small windows where challenger agencies can compete on stability and attention, not just price.
What CTV Consolidation Means for Media Buyers in Southeast Asia
The Alphonso story is US-centric, but the structural dynamics translate. Across Southeast Asia, CTV and connected screen inventory is still maturing — but the data infrastructure questions are arriving faster than the market expects. Platforms like Vidio in Indonesia and WeTV across the region are building their own first-party data stacks. Smart TV penetration is accelerating in Thailand and Vietnam. The ACR data moat that makes Alphonso valuable in the US will have regional equivalents within two to three years.
For media buyers running programmatic campaigns in the region, two things are worth doing now. First, audit which DSP partnerships have meaningful CTV inventory in-market versus which are reselling US-sourced audience segments onto APAC placements — a surprisingly common practice that inflates reach numbers while delivering limited local relevance. Second, watch which regional telcos and device manufacturers start making noise about their own data assets. That’s where the next round of structural consolidation conversations will happen, and being early to understand a platform’s data provenance is a genuine competitive advantage.
The Ad Stack Is Rationalising — Position Accordingly
The broader pattern behind both Alphonso and the WPP story is the same: the ad tech stack is contracting toward entities that either own irreplaceable data or own irreplaceable distribution. Everything in the middle is under margin pressure.
For brand-side marketing teams, this is a procurement and partnership question as much as a media question. Which ad tech vendors in your current stack have a defensible moat? Which are resellers with good dashboards? As consolidation continues — and Alphonso’s exit, whichever path it takes, will likely trigger comparable moves from other device-linked data businesses — the vendors that survive will be the ones that can demonstrate signal quality, not just inventory volume.
The agencies that win in this environment will be the ones who help clients navigate that distinction clearly, rather than optimising for the path of least resistance through established DSP relationships.
Key Takeaways
- Alphonso’s billion-dollar valuation is a bet on ACR data scarcity, not platform features — media buyers should understand which of their CTV partners own comparable first-party signal versus those who are simply aggregating it.
- Holdco legal pressure rarely triggers immediate client departures, but it does create margin negotiation opportunities and talent instability worth monitoring over a 12–18 month horizon.
- In Southeast Asia, the CTV data infrastructure race is 18–24 months behind the US — the time to build vendor evaluation frameworks is before those assets become expensive, not after.
The deeper question worth sitting with: as device manufacturers, telcos, and streaming platforms all move to monetise their own viewership data directly, what exactly is the long-term value proposition of a media agency that doesn’t have a proprietary view on signal quality? That’s not a rhetorical question — it’s an architecture one.
At grzzly, we work with marketing and media teams across Southeast Asia to cut through ad stack complexity and build programmatic strategies grounded in actual signal quality — not vendor relationships dressed up as strategy. If Alphonso’s story has you thinking harder about your own CTV and data partnerships, we’re happy to dig into it with you. Let’s talk
Sources
Written by
Neon GrizzlyFluent in DSPs, bid strategies, and the baroque architecture of the modern ad stack. Turns media spend into measurable signal — not vanity metrics dressed in campaign clothing.