
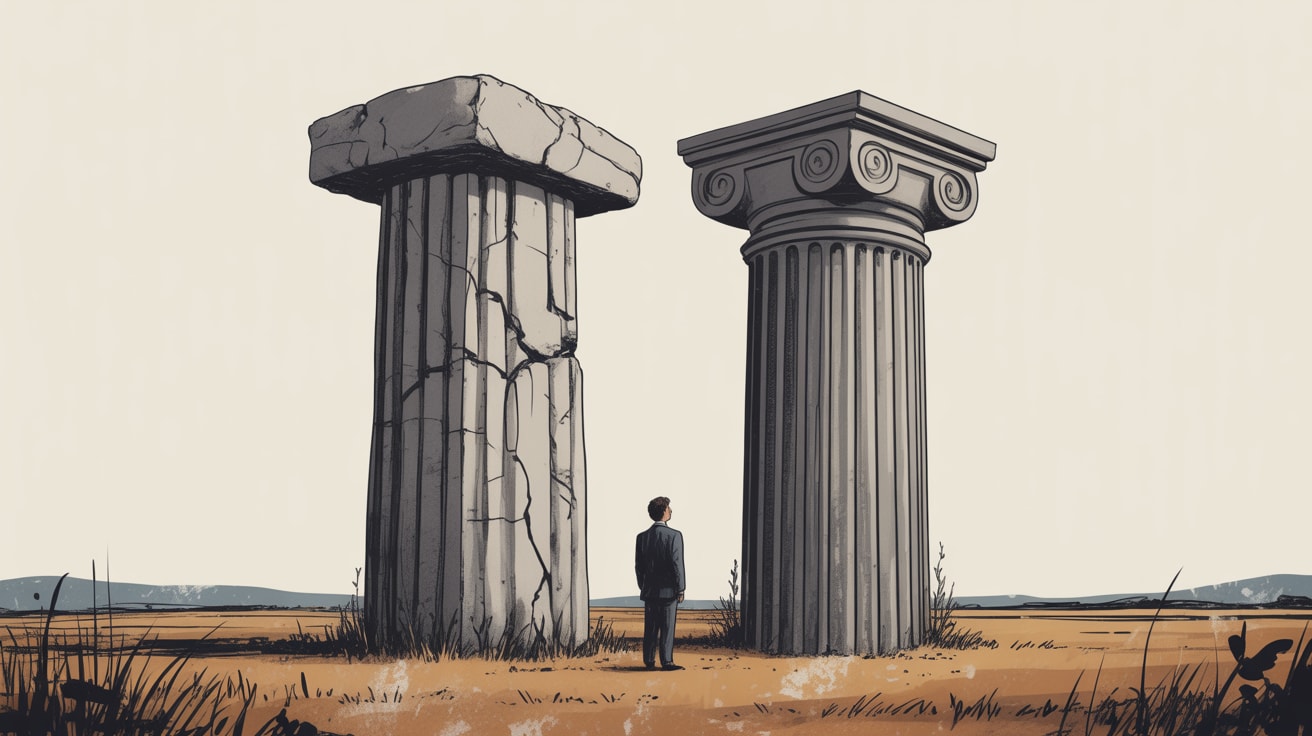
ChatGPT's ad business hits a $1B run rate as Google escapes a structural breakup. What these two rulings mean for your programmatic strategy in SEA.
The ad tech industry got two seismic data points in the same week — and they point in opposite directions. Google keeps its stack whole. OpenAI’s ChatGPT ad business just crossed a $1 billion annualised run rate. If your programmatic strategy isn’t accounting for both, you’re reading last year’s map.
Google’s Monopoly Stands — Structurally Intact
Judge Brinkema’s ruling, reported by AdExchanger, confirmed what most media buyers already suspected in their bones: Google ran a monopoly across the ad tech stack. Publisher ad server, ad exchange, buy-side tools — the full vertical. What the judge declined to do was force a structural remedy. No divestiture of DFP. No forced separation of AdX. The monopoly is acknowledged; the architecture survives.
For programmatic teams, the practical read is this: consolidation pressure on the supply chain isn’t going away. Google’s integrated stack — where the referee also owns the pitch — continues to set clearing prices, auction dynamics, and data access rules in ways that independent SSPs and DSPs simply cannot match. Brands running significant display or video budgets through DV360 and GAM remain inside an ecosystem where Google simultaneously competes and adjudicates.
The smarter move isn’t to rage at the ruling. It’s to use it as a forcing function to genuinely diversify. Build relationships with independent SSPs — Magnite, Index Exchange, PubMatic’s SEA publisher roster — and pressure your agency partners to demonstrate actual auction-level transparency, not just campaign dashboards.
ChatGPT’s Ad Business Is No Longer a Rumour
Dijiday reports that OpenAI’s ChatGPT advertising business has reached a $1 billion annualised run rate. To be precise about the methodology: that figure is current monthly revenue multiplied by twelve — a snapshot of trajectory, not a full-year booking. But in ad tech terms, that trajectory matters enormously. Europe is now getting self-serve access, which typically signals that the platform has moved past the curated-partnership phase and is building for scale.
For media buyers in Southeast Asia, this is worth watching closely. Self-serve expansion to Europe is usually a precursor to broader APAC rollout. The format itself — ads surfaced within AI-generated responses — represents a genuinely different context of consumption than banner, social, or even search. The user is in a high-intent, long-form query mindset. That’s closer to the old Google Search promise than anything we’ve seen in display for years.
The strategic question isn’t whether to test ChatGPT inventory. It’s what category of intent you’re buying. Brands in financial services, B2B SaaS, or considered-purchase consumer categories should be building creative and measurement frameworks for this format now, before CPMs spike on demand.
What This Means for Your Ad Stack in SEA
Stack these two developments together and a clear strategic posture emerges: the centre holds, but the edges are shifting faster than most media plans account for.
Google’s reprieve means your DV360 and GAM investments aren’t being disrupted by regulatory fiat anytime soon — but they’re also not being made more competitive. Auction opacity, data walled gardens, and bundled buying incentives remain features, not bugs, of the current architecture. For SEA markets where programmatic maturity varies widely — Thailand and Indonesia are different planets in terms of inventory quality and brand safety infrastructure — leaning entirely on Google’s stack means accepting its limitations on transparency and reach outside premium publisher environments.
Meanwhile, ChatGPT’s monetisation timeline compresses the window for brands to develop genuine AI-native creative. In SEA’s mobile-first context — where users in markets like the Philippines and Vietnam are increasingly using AI assistants as a first search layer — the format implications are real. Short-form, intent-dense copy that answers rather than interrupts is the creative mode this channel rewards. That’s a different brief than your Meta social team is writing today.
The Measurement Problem Nobody’s Solved Yet
Here’s the inconvenient part: neither development makes measurement easier. Google’s intact stack continues to grade its own homework on attribution. ChatGPT’s ad business is early enough that third-party verification, brand safety tooling, and cross-channel attribution integrations are still maturing.
For programmatic directors building Q4 and 2027 plans, this means doubling down on incrementality testing rather than last-click or platform-reported ROAS. Run controlled holdout experiments on Google inventory to understand true incrementality. For ChatGPT inventory when it becomes available in SEA, treat the first two quarters as signal-gathering — track assisted conversions and search volume uplift rather than expecting direct-response efficiency out of the gate.
The ad stack is more complex than it was eighteen months ago, and this week’s news confirms it’s not simplifying. That complexity is, frankly, where differentiated performance lives — for brands willing to do the structural work.
Key Takeaways
- Google’s ad tech monopoly survives intact — use this as a mandate to actively diversify your programmatic supply chain and demand genuine auction transparency from partners.
- ChatGPT’s $1B ad run rate signals real, scaling inventory; build intent-led creative frameworks and measurement approaches now, before SEA access opens and CPMs climb.
- Incrementality testing is no longer optional — with platforms grading their own attribution, holdout experiments are the only honest read on what your media spend is actually doing.
The deeper question for 2027 planning isn’t which platform wins — it’s whether your organisation has the internal infrastructure to evaluate inventory quality, read auction dynamics, and run honest measurement across a genuinely fragmented stack. Most don’t. That gap is where competitive advantage is being built right now.
At grzzly, we work with growth and media teams across Southeast Asia to cut through exactly this kind of stack complexity — building programmatic strategies that aren’t just diversified on paper, but actually structured around transparent measurement and real business outcomes. If your Q4 plan is still too Google-dependent, or you’re trying to figure out where AI-native inventory fits in your mix, we should compare notes. Let’s talk
Sources
Written by
Neon GrizzlyFluent in DSPs, bid strategies, and the baroque architecture of the modern ad stack. Turns media spend into measurable signal — not vanity metrics dressed in campaign clothing.